Cheap Pet Insurance for Dogs: A Veterinarian’s Guide to Affordable Coverage (2026)
As a veterinarian, I show you how to find cheap pet insurance for dogs in 2026 — the most affordable companies, cost-cutting strategies, and what to never sacrifice for a low price.
As a veterinarian, I hear a lot of owners say: “Pet insurance is too expensive — I can’t afford it.”
And I completely understand. When you’re budgeting for rent, food, and everything else life throws at you, another monthly bill can feel impossible. But here’s what I want you to know: pet insurance doesn’t have to be expensive.
In 2026, you can insure a dog for as little as $12–$30 per month — less than a streaming subscription. The key is knowing how to lower your premium without gutting your coverage.
In this guide, I’ll show you the cheapest pet insurance companies, the strategies to cut costs, and the traps to avoid so you don’t end up with “cheap” insurance that covers nothing.
🟢 How Much Does Cheap Dog Insurance Cost?
Here’s what budget-friendly coverage actually looks like in 2026:
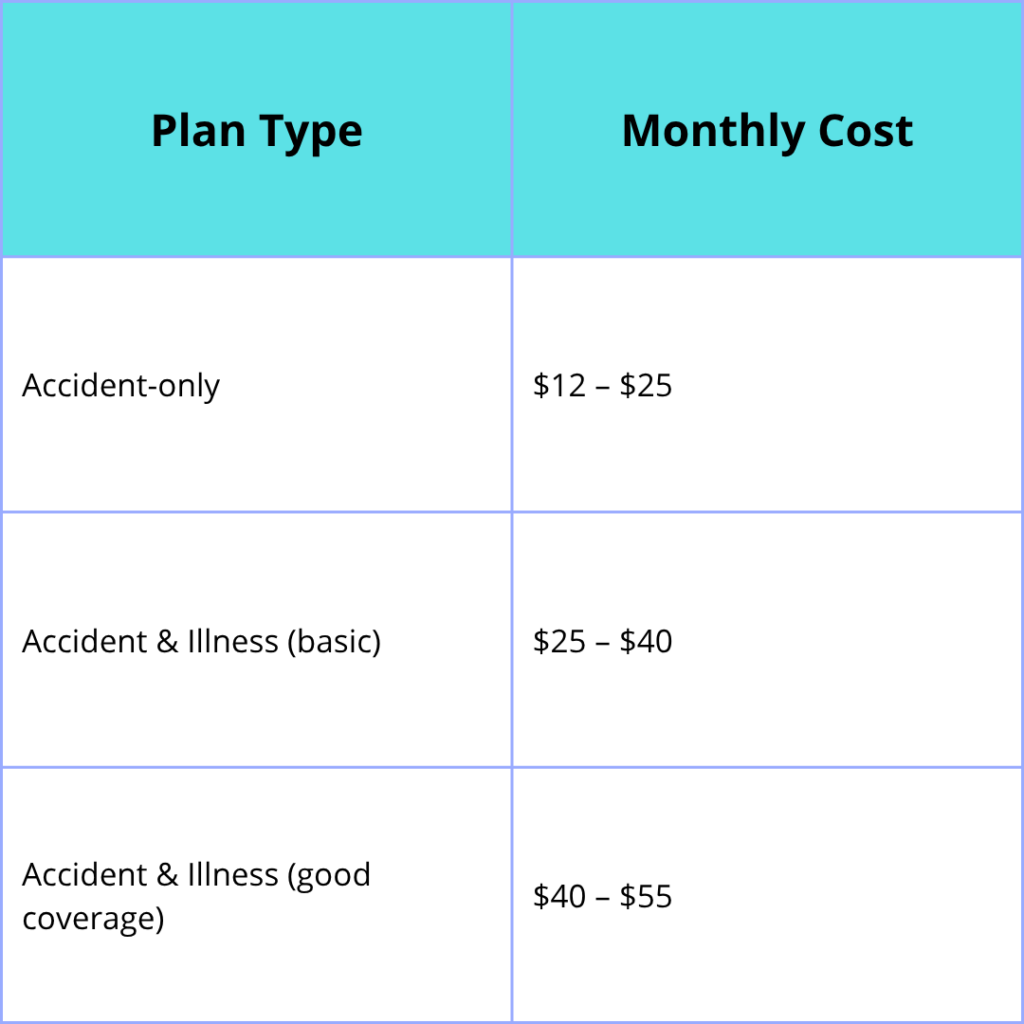
👉 The sweet spot: For most dogs, a good accident & illness plan runs $30–$45/month. That’s about the price of two coffee orders — for protection against $3,000–$10,000 emergencies.
🟡 The Cheapest Pet Insurance Companies of 2026
Based on analyses from U.S. News, Forbes, and NerdWallet, here are the most affordable companies:
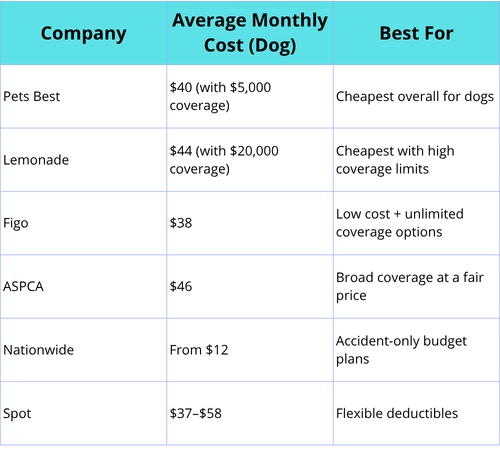
🔑 Key insight: “Cheapest” depends on your dog’s age, breed, location, and the coverage you choose. Get quotes from 3–4 companies before deciding — prices can vary by $20+/month for the same coverage.
These are the strategies I recommend to owners who want affordable coverage:
1. Buy While Your Dog Is Young
Premiums rise with age. Insuring a puppy can save you hundreds per year compared to insuring the same dog at age 8.
2. Choose a Higher Deductible
A $500–$1,000 deductible can cut your premium significantly. Pick a deductible you could realistically afford in an emergency.
3. Skip the Wellness Add-On
Vaccines and checkups are predictable — budget for them yourself. Insurance is for the unpredictable.
4. Pick a Lower Reimbursement Rate
Dropping from 90% to 70% reimbursement lowers your premium — but remember you’ll pay more out of pocket per claim.
5. Set a Reasonable Annual Limit
A $5,000 annual limit costs less than unlimited coverage — and still covers the vast majority of veterinary emergencies.
6. Look for Discounts
Many companies offer:
- Multi-pet discounts (10%+ for insuring multiple pets)
- Annual payment discounts (pay yearly instead of monthly)
- Bundling discounts (Lemonade bundles with renters/home insurance)
- Military or employee discounts
7. Choose Accident-Only for a Tight Budget
If even $30/month is too much, accident-only plans start around $12–$20/month. They won’t cover illnesses — but they’ll cover the most common catastrophic emergency: accidents.
🟠 What NOT to Sacrifice for a Cheap Plan
Cheap insurance is great — cheap insurance that doesn’t cover anything is not. Avoid these traps:
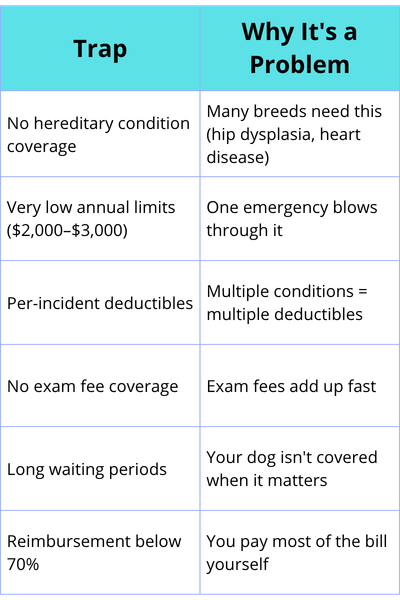
👉 My rule: A “cheap” plan is only worth it if it covers accidents, illnesses, and hereditary conditions — even with a high deductible and lower reimbursement.
🟡 Accident-Only vs. Accident & Illness: The Budget Choice
If money is tight, here’s how to decide:
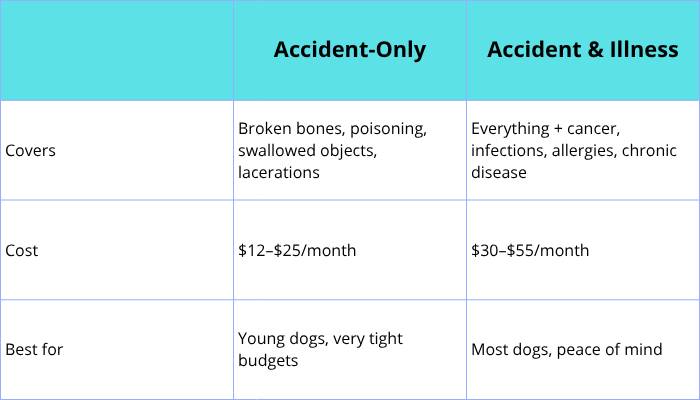
👉 My recommendation: Accident & illness is worth the extra $15–$20/month. Illnesses — not accidents — are what drive most big vet bills over a dog’s lifetime.
🔵 Real Example: The Budget Math
Let’s compare two approaches for a 2-year-old mixed-breed dog:
Option A — Accident-only plan
- Premium:
$15/month =$180/year - Year 3: Dog develops skin allergies (chronic illness) → not covered
- Owner pays
$800+ per year out of pocket
Option B — Accident & illness plan (high deductible)
- Premium:
$35/month =$420/year - Year 3: Dog develops skin allergies → covered at 80% after
$500deductible - Owner pays ~
$500first year, then 20% of treatment costs
👉 Over 5 years, Option B costs more in premiums — but if your dog gets sick even once, it saves you thousands. That’s the tradeoff.
🟣 How to Get a Quote (Step by Step)
- Gather your dog’s info — age, breed, weight, and your ZIP code
- Use a comparison tool — get quotes from 4–5 companies at once
- Choose the same coverage for each quote — so you compare apples to apples
- Adjust the deductible — try
$250,$500, and$1,000to see the price difference - Check discounts — multi-pet, annual payment, bundling
- Read the policy — exclusions, waiting periods, annual limits
- Buy early — before pre-existing conditions develop
❓ Frequently Asked Questions
What’s the cheapest pet insurance for dogs? Pets Best, Lemonade, and Figo consistently rank as the most affordable for dogs in 2026. Nationwide offers accident-only plans from around $12/month.
Can I get pet insurance for under $20/month? Yes — accident-only plans at major companies start around $12–$20/month. Accident & illness plans under $20 are rare but possible for young puppies with high deductibles.
Is cheap pet insurance worth it? It depends on what it covers. A cheap plan that covers accidents, illnesses, and hereditary conditions is worth it. A cheap plan with low limits and big exclusions may not be.
Do cheap plans cover hereditary conditions? Some do, some don’t. Always read the policy — breeds prone to hip dysplasia, heart disease, or allergies need this coverage.
What’s the best way to lower my pet insurance premium? Buy young, choose a higher deductible ($500–$1,000), skip the wellness add-on, and look for multi-pet or annual payment discounts.
Final Thoughts
As a veterinarian, my message is simple: you can afford to protect your dog. Cheap pet insurance exists — you just need to know where to look and what to prioritize.
Start with accident & illness coverage. Raise your deductible to lower the premium. Skip the extras you can budget for yourself. And never sacrifice coverage for hereditary conditions — that’s where the big bills come from.
A $35-a-month plan is a small price for knowing your dog will never be denied care because of money.