Is Pet Insurance Worth It? A Veterinarian’s Honest Cost-Benefit Analysis (2026)
As a veterinarian, I break down whether pet insurance is worth it in 2026 — real costs, real claims, real scenarios — so you can decide with confidence.
As a veterinarian, I get asked this question more than almost any other: “Is pet insurance really worth it?”
It’s a fair question. Insurance is a monthly expense you hope you never need — and when your pet is healthy, it can feel like throwing money away. But I’ve also seen the other side: owners facing a $6,000 surgery bill with no plan, forced to make impossible choices.
Here’s the honest truth: pet insurance is not for everyone — but for most pet owners, the math works out in its favor. It depends on your pet, your finances, and your risk tolerance.
In this guide, I’ll give you the real numbers, the real scenarios, and a clear framework to decide whether pet insurance is worth it for you.
🟢 The Real Numbers: What Pet Insurance Costs
Let’s start with the facts. Based on 2026 industry data (NAPHIA State of the Industry Report):
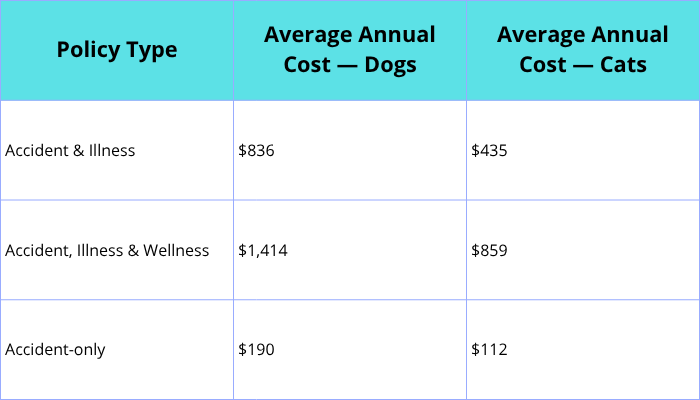
Monthly equivalent (accident & illness):
- Dogs: roughly
$35–$70depending on age and breed - Cats: roughly
$20–$35
🔑 Key insight: The cost of insurance is predictable. The cost of a veterinary emergency is not. A single ACL surgery runs $3,000–$5,000. Cancer treatment can exceed $10,000. One emergency can equal years of premiums.
🟡 What Pet Insurance Covers (and Doesn’t)
Covered (accident & illness plans)
- Accidents (broken bones, foreign body ingestion, poisoning)
- Illnesses (infections, cancer, diabetes, kidney disease)
- Hereditary and congenital conditions (with most plans)
- Diagnostic tests, surgery, hospitalization, medication
- Emergency care
Not Covered (standard plans)
- Routine/preventive care (vaccines, dental cleanings) — unless you add a wellness rider
- Pre-existing conditions
- Exam fees (some plans)
- Breeding costs, cosmetic procedures
🔴 The Most Common Veterinary Bills (What You Could Face)
Here’s what I see in practice every day. These are real costs pet owners face without insurance:
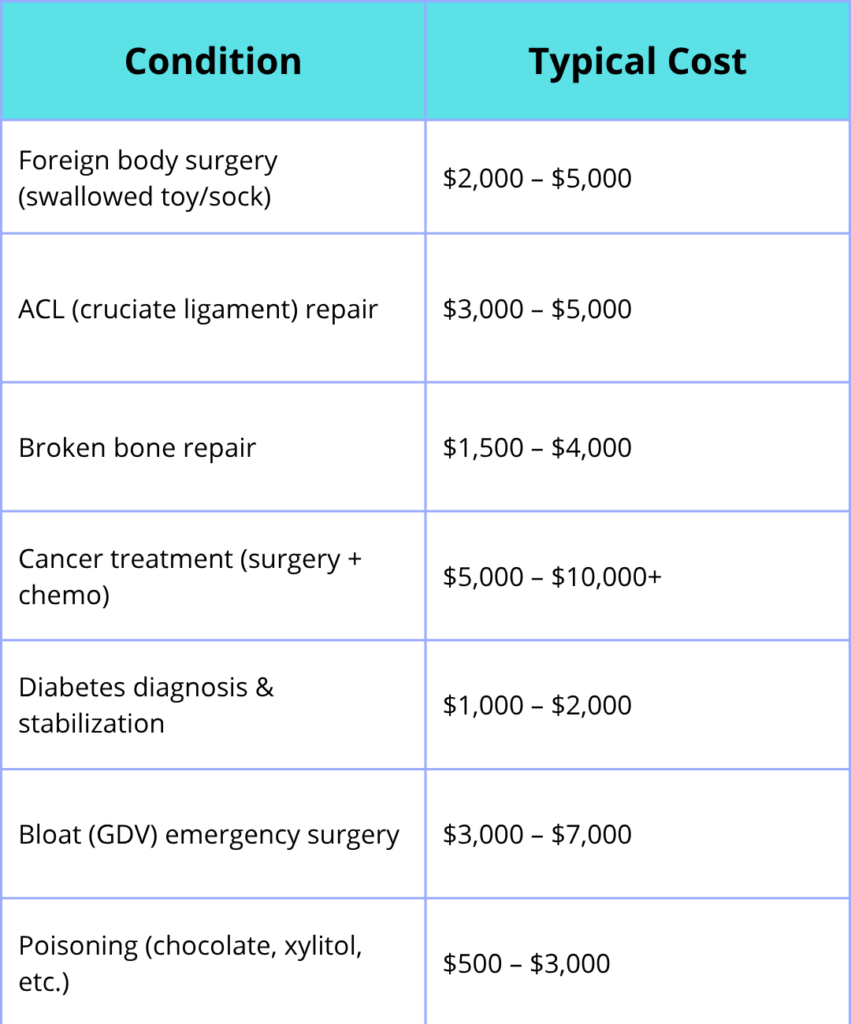
👉 The math: One moderate emergency easily pays for 3–5 years of premiums.
🟠 The Scenarios: When Insurance Is Worth It
✅ Worth It If…
- You couldn’t afford a sudden
$3,000–$10,000bill — insurance is a safety net you can actually afford - You have a young pet — you lock in low rates before conditions develop
- Your breed is prone to costly conditions — French Bulldogs (respiratory), Golden Retrievers (cancer), Great Danes (bloat), German Shepherds (hip dysplasia)
- You want peace of mind — knowing you’ll never have to choose between finances and your pet’s life
- You’re the type who wants protection — you probably have health insurance for yourself for the same reason
❌ Maybe Not Worth It If…
- Your pet is senior with many pre-existing conditions — most won’t be covered; premiums are high
- You have a healthy pet and can comfortably self-fund — a dedicated savings account can work if you’re disciplined
- Your budget is very tight — a premium you can’t afford is worse than no insurance; consider accident-only plans
🔵 The “Self-Insurance” Alternative
Some owners choose to “self-insure” — putting the monthly premium into a savings account instead.
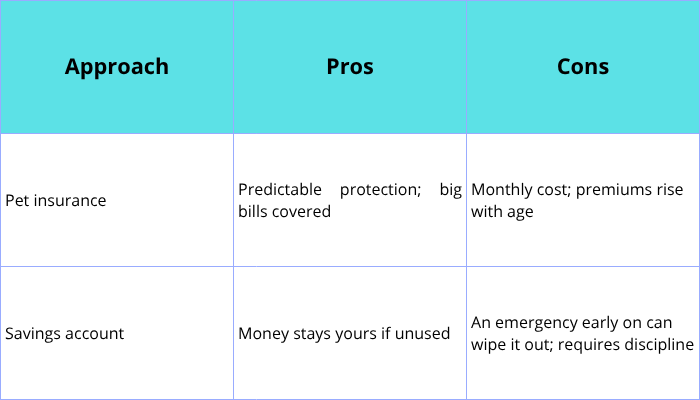
🔑 Key insight: Self-insurance works only if you have time to build the fund before an emergency strikes — and the discipline to never touch the money for anything else. Most people don’t have 2–3 years of premiums saved when their dog swallows a sock.
🟡 How to Make Pet Insurance Worth It
If you decide to get coverage, here’s how to maximize its value:
1. Buy Young
Premiums rise with age. A puppy policy is dramatically cheaper than the same policy at age 8.
2. Choose the Right Deductible
- Higher deductible (
$500–$1,000) = lower premium - Lower deductible (
$100–$250) = higher premium - Pick what you could actually afford to pay out of pocket
3. Go for 90% Reimbursement
The difference between 70% and 90% can be thousands of dollars on a big claim — worth the higher premium.
4. Skip the Wellness Add-On (Usually)
Routine care (vaccines, checkups) is predictable — you can budget for it. Insurance is best used for the unpredictable. (Add wellness only if it’s genuinely cheaper than paying out of pocket.)
5. Read the Fine Print
Know the waiting periods, exclusions, and annual limits before you need them.
🟣 Real-Life Example: The Math
Let’s compare two dogs over 5 years:
Dog A — Insured
- Premium:
$50/month =$600/year =$3,000over 5 years - Year 3: ACL surgery
$4,000→ insurance covers 90% =$3,600back - Net result:
$3,000paid in premiums,$3,600returned → insurance saved you$600(and that’s before considering any other claims)
Dog B — Not Insured
- Saves
$600/year =$3,000saved - Year 3: ACL surgery
$4,000→ pays$4,000out of pocket - Net result:
$1,000in the red — and that’s one incident
👉 One moderate emergency flips the math in insurance’s favor. And if your dog has two incidents in a lifetime (very common), insurance wins decisively.
❓ Frequently Asked Questions
Is pet insurance worth it for a healthy puppy? Yes — this is the optimal time to buy. You lock in the lowest rates and avoid pre-existing exclusions before any health issue develops.
At what age does pet insurance stop being worth it? Around 8–10 years, premiums climb sharply and more conditions become pre-existing. That said, older pets are exactly when big medical bills become more likely — evaluate carefully.
Can I get pet insurance for an older pet? Yes, but expect higher premiums and exclusions for pre-existing conditions. Some companies (like Pumpkin) have no upper age limit.
Does pet insurance cover routine checkups? Not on standard plans. You can add a wellness rider for vaccines and checkups, but it’s usually better to budget for routine care yourself.
What’s the best pet insurance company? It depends on your pet’s age, breed, and budget. Compare quotes from 3–4 companies (ASPCA, Embrace, Lemonade, Trupanion, Figo are consistently top-rated).
Final Thoughts
As a veterinarian, here’s my honest bottom line: pet insurance is worth it for most pet owners — especially those who couldn’t absorb a sudden multi-thousand-dollar bill.
The math is simple: veterinary care costs have risen dramatically, one emergency can cost more than a decade of premiums, and insurance turns that unpredictable catastrophe into a manageable monthly cost.
It’s not a perfect product, and it’s not for everyone. But if you ask me — a vet who has seen too many owners forced to choose between their wallet and their best friend — the peace of mind alone is worth it.